A hospital stay rarely comes with a warning, and for a home with two adults and two children, one large bill can undo years of steady saving. Medical costs in India keep climbing, which is why so many parents ask how much sum insured for a family of four is actually enough. The answer depends on where you live, how healthy everyone is and what kind of plan you pick.
Getting these choices right while picking a mediclaim policy for family means you can focus on recovery, not on paperwork or payments. This blog walks you through each step of choosing a plan, from understanding your needs to checking claim support.
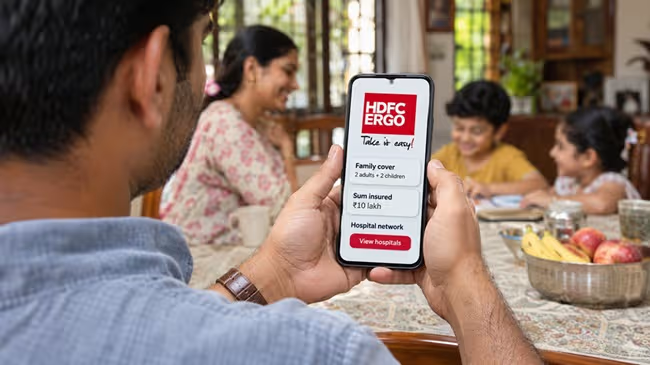
Before you look at a single plan, think about the four people you are protecting. Their ages, medical history and daily routines shape the family health insurance plan that will actually suit you.
Ask yourself these questions first:
Clear answers to these save you from buying cover that looks good but fits poorly.
A floater means one sum insured is shared by everyone, while individual plans give each person a separate limit. A mediclaim policy for a family usually follows the floater model, which keeps premiums manageable for most households.
| Feature | Family floater | Individual plans |
| Sum insured | Shared by all four | Separate for each person |
| Premium | Generally lower | Generally higher |
| Best suited for | Young, healthy families | One high-risk member |
If one adult has ongoing health concerns, a floater plus a separate individual plan for that person often works better. Otherwise, a single floater is usually enough for a young family.
Cover that feels generous today can run short in five years, as hospital rates rise every year. When deciding how much sum insured to buy for a family of four, look at your city, local treatment costs, and any employer cover you already have.
A super top-up plan is a practical way to raise your cover later at a modest cost, so you need not buy the highest amount on day one.
Waiting periods decide when certain claims become payable, so it helps to read them before you pay. Before you buy family health insurance, check these points closely:
Certain insurers will shorten waiting periods for a slightly higher premium, which is worth asking about if someone in the family already has a health condition.
A plan is only as good as its claim experience. A reliable mediclaim policy for family should offer a wide network of hospitals near your home and a smooth cashless process. Check the insurer’s claim settlement ratio and read recent customer reviews, and confirm that the helpline works round the clock.
It also helps to ask a friend or relative who has made a claim how it went, as their experience often tells you more than a brochure.
The cheapest premium is not always the best choice. Compare what each plan gives you for the price, since a slightly higher premium often brings far more useful cover. These extras are worth looking for:
Add up the likely benefits, not just the price, and the better plan usually becomes clear.
Choosing the right cover takes patience, but the effort pays off the moment a medical need arises. Begin with your family’s health needs, pick the plan type that suits you and settle on a sum insured that matches your city and budget.
Read the waiting periods carefully, check the hospital network and compare the benefits before you pay. Follow these steps, and you will end up with a policy that protects both your children and your savings for many years to come.